Assessment of associated credit risk in the supply chain based on trade credit risk contagion
Curious4:21CCAI
paperi.ai
0:00 / 0:00
Xiaofeng Xie, Fengying Zhang, Li Liu, Yang Yang, Xiuying Hu
A company can look safe on its own and still become dangerous to a bank when a business partner gets into trouble. This study asks how financial risk travels through the supply chain before the damage is obvious.
Assessment of associated credit risk in the supply chain is a challenge in current credit risk management practices. This paper proposes a new approach for assessing associated credit risk in the supply chain based on graph theory and fuzzy preference theory. First, we classified the credit risk of firms in the supply chain into two types, namely firms’ “own credit risk” and “credit risk contagion”; second, we designed a system of indicators for assessing the credit risks of firms in the supply chain and used fuzzy preference relations to obtain the fuzzy comparison judgment matrix of credit risk assessment indicators, on which basis we constructed the basic model for assessing the own credit risk of firms in the supply chain; third, we established a derivative model for assessing credit risk contagion. On this basis, we carried out a comprehensive assessment of the credit risk of firms in the supply chain by combining the two assessment results, revealing the contagion effect of associated credit risk in the supply chain based on trade credit risk contagion (TCRC). The case study shows that the credit risk assessment method proposed in this paper enables banks to accurately identify the credit risk status of firms in the supply chain, which helps curb the accumulation and outbreak of systemic financial risks.
Transcript
A company can look safe on its own and still become dangerous to a bank when a business partner gets into trouble. This study asks how financial risk travels through the supply chain before the damage is obvious. Supply chains now connect firms across industries, regions, and many business relationships.
They are no longer a row of separate companies; they are a connected system. That connection lets credit trouble move from one firm to another, creating a network of associated risk. Because the effect can directly endanger banks that lend to these firms, banks must look beyond each borrower alone.
The study separates two sources of danger: a firm’s own credit risk, caused by internal weaknesses or changes in the wider economy, and risk caused by other firms with which it has commercial credit relationships. The second kind begins when one firm cannot meet its obligations and makes another firm more likely to fail.
In the network, firms are the points, and the relationships between them are the paths risk can follow. Think of the supply chain like a row of shops that let one another buy now and pay later. If one shop falls into financial trouble, the shop waiting for payment can be pulled into trouble too.
The direction of each relationship records which firm extends trade credit and which firm receives it, showing the flow from the creditor to the recipient. The relationship's strength is represented by its weight: it records both the line of trade credit and the duration before payment.
Risk may travel not only to a direct business partner but also through several connected firms, while the analysis keeps the firms and their credit agreements unchanged. The amount of risk passed along depends on the shape of the network, where the trouble starts, and how much danger the affected firms already carry.
The model assigns each directed relationship a value that represents how strongly one firm's credit risk affects the other. A value of zero point four five means a forty-five percent chance that one firm's own risk reaches the other. Credit risk is treated as a supply-chain relationship, not just a company balance sheet: the assessment combines the wider economy, ties between firms, the firm’s finances, and the financial health of associated firms.
The table makes clear that even personal relationships and contract history are part of that risk. For a lender, this is a step-by-step route from a company’s financial information to a credit-risk assessment across its supply chain. It matters because it combines hard figures with less measurable business qualities before judging how financial trouble might spread between connected firms.
In the automotive supply chain examined here, every firm faces some risk coming from associated firms, though the increase is different for each one. The core firm, called S4 in the study, is least affected because it has stronger resistance to risk.
Another firm, S8, is most exposed because it extends more and larger amounts of trade credit and has weaker resistance of its own. Credit problems can spread between firms through trade credit, turning one company’s trouble into a wider supply-chain crisis. This network maps those possible links among eight firms, including pathways that connect distant parts of the chain rather than leaving risk isolated.
The model changes the picture for the upstream supplier P2: its assessed credit risk rises significantly to zero point seven four zero zero two. That increase comes from including the effect of the Petrochemical Company P1’s credit risk on P2, rather than judging P2 without its business connection.
The approach has a clear boundary: it is built only for networks linked by trade credit. Credit can also travel through more complicated economic and social relationships, which this model does not yet cover. So this is a preliminary exploration, with future work aimed at assessing firms under different economic and social supply-chain relationships.
The central lesson is simple: judging each company alone misses part of the danger. Following who extends credit to whom can reveal which firms are most exposed and help banks contain wider financial shocks.
A derivative work by Paperi · AI-generated script, voice and captions
· pages and figures unaltered
Made with Paperi.
Drop in a research PDF — get a narrated video walkthrough like this one,
with highlights that follow the narration. Free to start.
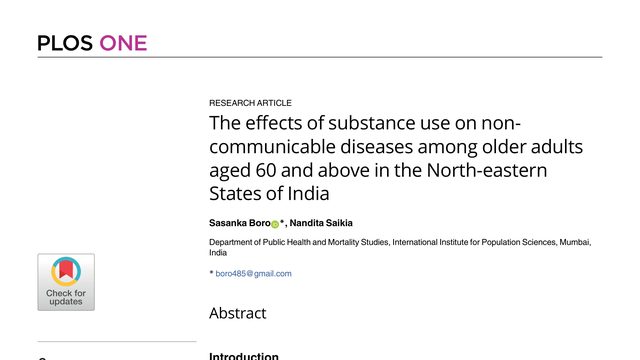
For older adults in North-eastern India, tobacco and alcohol are not just habits carried into later life. This study finds they are closely tied to several chronic illnesses, with one especially striking link to cancer.In Northeast India, older adults who have used tobacco or alcohol show striking associations with chronic diseases, including a nearly twenty-fold higher odds of cancer for people with past smoking behaviour. But this is an association, not proof of causation.
Michael Mollenhauer, Abdullah Irfan, Xi Cao, Supriya Mandal, Wolfgang Pfaff
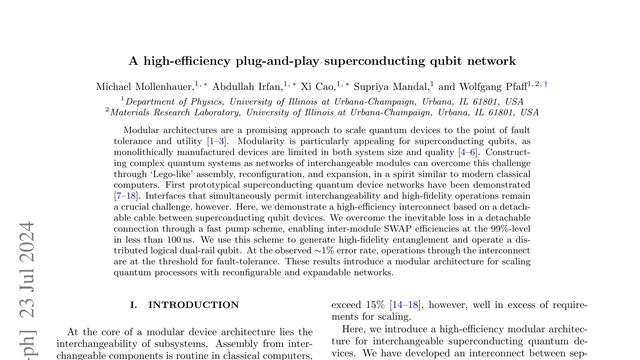
What if a quantum computer did not have to be built as one giant, delicate object? This experiment shows that separate quantum devices can be connected by a cable, unplugged, and still exchange information with about one percent loss.What if scaling a quantum computer looked less like fabricating one enormous chip, and more like plugging together replaceable modules? This paper shows a detachable cable moving quantum information with roughly one-percent loss in under one hundred nanoseconds.
Yan Huang, Yao Deng, Xiaoming Jiang, Yiyuan Chen, Tianxin Mao, Yong Xu, Caihong Jiang, Hengyi Rao
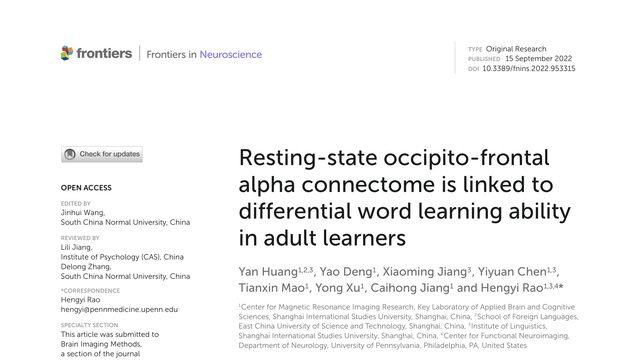
Why can one adult learn a new word almost effortlessly while another struggles? This study suggests the answer may partly lie in how two distant parts of the resting brain keep time together.Some adults learn new words much more easily than others. This study asks whether that difference can already be seen in the resting brain, before the learning task even begins.
 4:23